OPERATIONS PERSPECTIVE | "SPIRIT AIRLINES: WHEN THE ULTRA-LOW-COST MODEL LOSES ITS OPERATIONAL FOOTHOLD"
Perspective from an Operational Excellence consultant (Master Black Belt).
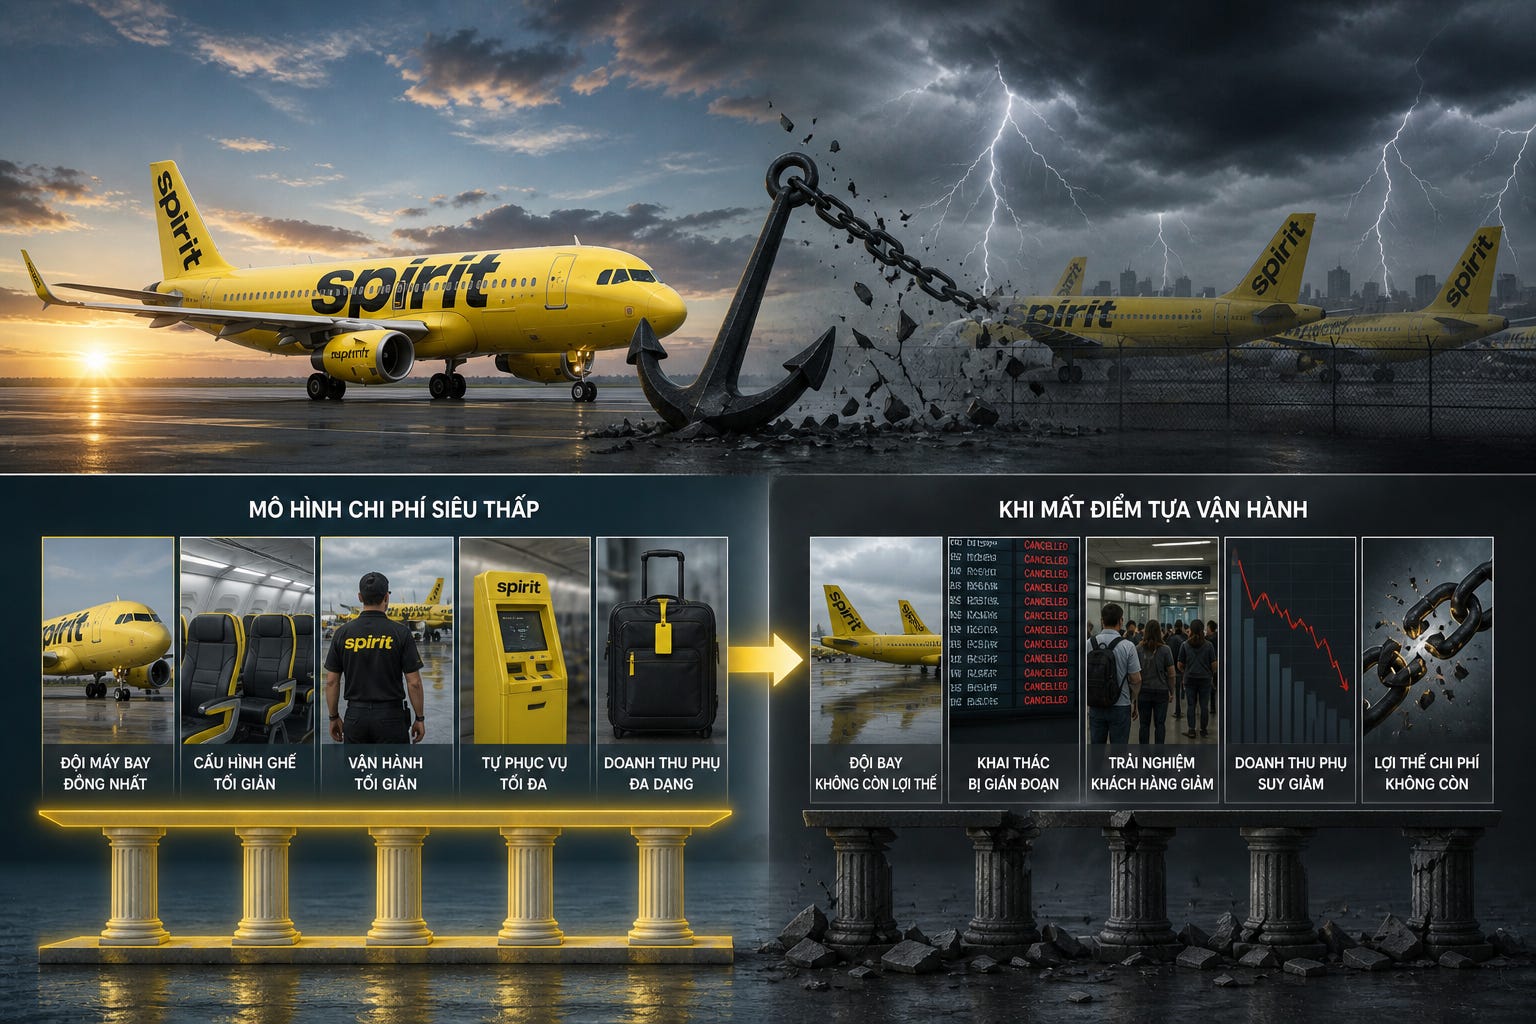
On May 2, 2026, at 3 a.m. Eastern Time, Spirit Airlines officially ceased all flight operations. 17,000 people, including 14,000 full-time employees and thousands of subcontractors, received notice just one hour before the decision was announced. This was the first shutdown of a major U.S. airline since Midway Airlines closed after the events of September 11, 2001. The story of Spirit Airlines is not just an ordinary bankruptcy in the airline industry, but a profound lesson in how an operating system, no matter how leanly designed, can still collapse when its underlying foundational assumptions are broken simultaneously from multiple directions.
As someone working in operations optimization, this article is not intended to judge or assign blame to any individual or organization. Instead, it will analyze Spirit Airlines' 43-year journey entirely through an operations lens, exploring how operating variables interact with one another, how one-dimensional optimization can create blind spots, and how operational resilience plays a decisive role in the survival of a business. The sole goal is to draw valuable insights for any organization operating in a highly volatile environment.
THE HISTORY AND OPERATING PHILOSOPHY OF SPIRIT AIRLINES
Spirit Airlines began as Charter One Airlines in 1983, operating under a charter flight model in the Detroit, Michigan area, spun off from the Clippert Trucking Company. For nearly its first decade, the airline served short- and medium-haul routes at a small scale, focusing on customers seeking low-cost fares for leisure travel to Las Vegas, Atlantic City, and the Bahamas. In May 1992, it officially changed its name to Spirit Airlines and shifted to a scheduled airline model, marking the first turning point in its journey.
The most important transformation came under CEO Ben Baldanza (2006 to 2015), when Spirit Airlines became the first and purest Ultra Low Cost Carrier (ULCC) in the United States. The operating philosophy of the ULCC model can be understood through one core principle: completely separating the base fare from all ancillary services (the “Bare Fare” unbundling model from 2007), thereby bringing fares down to the lowest possible level to attract the most price-sensitive customer segment. Every service, from checked baggage, carry-on baggage, seat selection, and food and beverages, to printing boarding passes at the airport, became a separately charged source of ancillary revenue. This model pushed Spirit's ancillary revenue to over 40% of total revenue under Baldanza, and it continued to rise to approximately 50 to 59% in 2024 (according to IdeaWorks data), one of the highest ratios in the global airline industry.
From an operations perspective, Spirit's ULCC model was built on several clear pillars. The first was optimizing Cost per Available Seat Mile (CASM). Spirit kept CASM at the lowest level in the industry by operating a common fleet (fleet commonality) of narrow-body Airbus A320 family aircraft, maximizing seat density per aircraft, minimizing gate turnaround time, and eliminating any costs not directly serving the movement of passengers from point A to point B. The second was maximizing fleet capacity by increasing average daily block hours per aircraft (aircraft utilization), thereby spreading fixed costs across more flights. The third was a point-to-point network structure instead of the traditional hub-and-spoke model, helping reduce central airport operating costs and shorten aircraft time on the ground.
This philosophy, in purely operational terms, is a classic example of optimizing a single variable: unit cost. Spirit Airlines had turned itself into an operating machine precisely calibrated to perform most efficiently within a very specific range of conditions: stable low-to-moderate fuel prices, strong demand from the price-sensitive customer segment, a fleet operating at high utilization, and limited direct price competition from legacy carriers. When all of these conditions were met, the operating model with thin margins but high volume, Spirit demonstrated its strength for many years. However, this deep one-dimensional optimization also created a systemic vulnerability that only became visible when the boundary conditions changed.
THE DIVERGENCE BETWEEN COST AND REVENUE, THE FIRST SIGN OF OPERATIONAL STRAIN
To understand the collapse of Spirit Airlines, you need to analyze the two most core operating metrics in the airline industry: CASM (Cost per Available Seat Mile) and RASM (Revenue per Available Seat Mile). The relationship between these two metrics determines the operating profit margin, and when the gap between them narrows or reverses, that is the earliest early warning signal any operations professional needs to watch.
Since Q1 2019, Spirit Airlines' CASM has increased by about 40%, nearly double the rate of inflation. This figure reflects simultaneous increases across multiple cost categories: highly volatile fuel prices after the pandemic, labor costs rising under new labor agreements across the industry, higher maintenance costs as the fleet aged and especially when the engine recall occurred, and higher aircraft lease costs as the leasing market tightened. Specifically, adjusted CASM (excluding fuel) rose from about 5.67 cents in Q4/2019 to 7.97 cents in 2024. Meanwhile, RASM increased by only about 8% over the same period, an increase even less than half the overall inflation rate. In absolute terms, by the end of 2024, Spirit's RASM stood at 9.27 cents while CASM had risen to 11.35 cents, meaning Spirit was spending more than it earned on every available seat mile.
The root cause of this CASM/RASM divergence lies on both sides. On the cost side, many factors were beyond the airline's direct control: fuel prices are a global variable, labor costs were under pressure across the industry, and maintenance costs depended on the engine manufacturer. However, on the revenue side, the stagnation in RASM reflects a structural shift in the competitive environment. The legacy carriers in the United States successively introduced Basic Economy fares (starting with Delta Air Lines in 2012, followed by American Airlines and United Airlines), essentially copying Spirit's stripped-down service model but built on a larger network, a stronger loyalty program, and a more solid brand reputation. When a passenger can buy a Basic Economy ticket on American Airlines or Delta Air Lines for only slightly more than on Spirit but fly with an airline offering broader connectivity and lower risk of disruption, Spirit's price advantage is seriously eroded.
From an operations perspective, this is a phenomenon of “reverse commoditization”. Normally, premium products become commoditized when low-cost competitors enter the market. But in this case, the legacy carriers commodified the low-cost product, creating a version “cheap enough” of exactly what Spirit sells, while retaining the system advantages Spirit does not have. As a result, Spirit lost the ability to grow RASM (because the market would not accept higher prices for the ULCC product when alternatives exist) but still had to bear rising CASM (because operating costs do not discriminate between carriers).
This divergence did not happen overnight. It accumulated gradually from 2019, became more severe through the Covid 19 pandemic period, and by 2024, the gap had widened to the point where Spirit's operating margin turned deeply negative. In 2024, Spirit's total operating revenue was $4,913.4 million, down 8.4% year over year, while the airline reported a net loss of $1,229.5 million (about $1.2 billion). This is a figure that shows the operating model had lost its ability to self-balance.
THE PRATT & WHITNEY GTF ENGINE ISSUE AND ITS IMPACT ON OPERATING CAPACITY
If the CASM/RASM divergence was the chronic strain, then the Pratt & Whitney GTF (Geared Turbofan) engine recall was the acute shock striking directly at Spirit's operating capability. This is a classic example of how dependence on a critical equipment supplier can create systemic operational risk.
Spirit Airlines operates a fleet including Airbus A320neo and A321neo aircraft equipped with Pratt & Whitney PW1100G JM engines, part of the GTF family. In July 2023, parent company RTX discovered an issue related to a powdered metal manufacturing issue in the high pressure compressor disk, and a large-scale global inspection and replacement program was launched. For Spirit, the direct consequence was 38 narrow-body Airbus aircraft grounded, and all 79 GTF engines in its fleet fell within the scope of the recall program. Over 50% of Spirit's fleet consists of A320/A321neo aircraft using GTF engines, making the airline particularly vulnerable.
The operational impact can be measured through aircraft utilization: from 11.1 block hours per day per aircraft in 2023, the figure fell to 9.9 hours in 2024. A decline of 1.2 flight hours per day per aircraft may sound small, but multiplied across the entire fleet and over a full year, it represents millions of lost Available Seat Miles. For a ULCC operating on thin profit margins, every hour an aircraft sits on the ground without generating revenue is an enormous opportunity cost, because fixed costs (depreciation, aircraft leases, insurance) continue to accrue whether the aircraft takes off or not.
The knock-on effect across the entire operating chain was significant. Spirit had to furlough 170 pilots effective September 1, 2024 due to insufficient aircraft to maintain its schedule, followed by approximately 300 additional pilots from January 2025. This affected not only personnel costs but also created operational risk when restoring schedules: pilots returning after an extended leave require retraining and competency checks before returning to operations, creating a lag in the capacity recovery process. Compensation from Pratt & Whitney (through its International Aero Engines affiliate, abbreviated IAE) was around $150 to $195 million (some sources cite up to $200 million), but compensation cannot make up for flights not operated, ancillary revenue not generated, and the deterioration in customer experience when flights are canceled or rescheduled.
From an operations perspective, the GTF issue exposed an important characteristic in Spirit's operating system architecture: fleet commonality, long considered a strength, became a weakness when a systemic risk materialized. When the entire fleet uses the same engine type from the same supplier, a single quality issue can affect the entire operating capacity, with no backup fleet with different engines to substitute. This is the classic trade-off between efficiency and resilience in operating system design, in which Spirit had maximized efficiency.
THE BLOCKED MERGER AND THE NONEXISTENT ALTERNATIVE PATH
In July 2022, JetBlue Airways proposed to acquire Spirit Airlines for an equity value of $3.8 billion (adjusted enterprise value of $7.6 billion). From a pure operations perspective, this deal would have created the fifth-largest airline in the United States with complementary networks: JetBlue was strong at major East Coast airports and transcontinental routes, while Spirit was strong on short- to medium-haul routes and secondary airports. The combination could have addressed Spirit's RASM problem (through JetBlue's stronger network and brand) while helping JetBlue reduce CASM (through a larger fleet scale and Spirit's low-cost operating expertise).
On January 16, 2024, a federal judge blocked the deal on the grounds that it would likely push fares higher and reduce competition. Regardless of the rationale, the operational consequence was clear: Spirit lost its restructuring path through merger, an option many ULCCs around the world have used successfully when the standalone model was no longer sustainable. More importantly, Spirit had spent nearly two years (2022 to 2024) focusing management resources and organizational energy on pursuing the merger, while fundamental operational problems (the CASM/RASM divergence, the engine issue, shifting competition) continued to accumulate. When the deal was blocked, Spirit had to face all the delayed problems simultaneously, but now with weaker financial resources and a weaker market position.
This is an important operations lesson: when an organization bets its entire escape strategy on a single exit strategy, and that option fails, the organization often ends up in a worse position than before it began pursuing that option, because time and resources have been consumed while the root problems went unaddressed. In operations management, the principle of parallel contingency planning exists precisely to avoid this situation. However, it must be acknowledged fairly that simultaneously pursuing a merger and a deep operational restructuring is extremely difficult in terms of governance and resource allocation, especially for an organization of Spirit's size.
THE FIRST BANKRUPTCY AND THE QUESTION OF OPERATIONAL RESTRUCTURING
On November 18, 2024, Spirit Airlines filed for bankruptcy protection under Chapter 11 of the U.S. Bankruptcy Code for the first time. The carrier spent 87 days in the protection process and emerged in March 2025. In terms of timing, 87 days was a notably swift process, made possible because Spirit had negotiated a pre-negotiated restructuring framework with most of its bondholders before filing.
However, from an operational perspective, the most notable feature of this first restructuring was its scope: it was primarily a balance sheet restructuring, focused on swapping secured bond debt for equity (debt for equity swap) in the reorganized company. The core operational questions — including whether the ULCC business model remained viable in the new competitive context, whether the cost structure needed fundamental change, whether the fleet strategy needed adjustment, and what level of fuel hedging capability needed to be built — were not addressed to the necessary degree.
This created a paradox: Spirit emerged from bankruptcy with a leaner balance sheet, but with the same operating model that had led to bankruptcy. If the operating model is the operating system of an organization, then the first restructuring was like deleting junk data to free up memory, without updating or fixing the operating system. The computer runs faster temporarily, but the old bugs remain and will recur.
Actual results confirmed this: in just the three months from March to June 2025 after exiting Chapter 11, Spirit lost an additional $257 million (versus a forecast net profit of $252 million for full-year 2025). This shows the problem lay not in the financial structure but in the operating structure and business model. A clean balance sheet is of no help when a business continues to operate with CASM systematically higher than RASM.
THE SECOND BANKRUPTCY AND A RESTRUCTURING PLAN BASED ON A SINGLE-VARIABLE ASSUMPTION
On August 29, 2025, Spirit Airlines filed for Chapter 11 bankruptcy protection for the second time, less than a year after the first. This time, the scale of the problem was significantly larger: total debt of $8.1 billion versus total assets of $8.6 billion (per court filings), meaning the safety cushion between assets and debt was only about $500 million — an extremely thin margin of safety for an airline with operating costs of billions of dollars per year.
The second restructuring plan was built on one critical underlying assumption: jet fuel prices at $2.24 per gallon for 2026 and $2.14 for 2027 (per the March SEC filing). This was the price level at which, with other operational adjustments, Spirit could achieve a positive operating profit margin of about +0.5% upon exiting bankruptcy. In other words, the entire recovery plan rested on the assumption that fuel prices would remain at or below historical averages.
From an operations expert's perspective, this is the point that warrants close analysis. Jet fuel prices are the highest volatility variable in any airline's cost structure, typically accounting for 25 to 35% of total operating costs. Building a recovery plan with only a 0.5% profit margin based on an assumption about the most volatile variable, without a meaningful fuel hedging mechanism, means the plan is viable only within a very narrow range of scenarios. Any event pushing fuel prices above the assumed level would wipe out the profit margin and push the carrier back into loss-making territory.
This is not a criticism, but an observation about the structure of the plan. In practice, airlines in bankruptcy have very limited access to the fuel derivatives market on favorable terms, due to low credit standing and lack of collateral. However, this very constraint underscores the importance of designing a restructuring plan with multi-scenario planning for fuel prices, including adverse scenarios, and identifying the breakeven thresholds at which the plan needs to be adjusted.
THE STRAIT OF HORMUZ CRISIS AND AN OUT-OF-MODEL EVENT
The event that completely changed the picture was the crisis in the Strait of Hormuz. Since February 28, 2026, when military conflict erupted in the region, oil shipments through the strait have been severely disrupted, creating what analysts call a “dual blockade.” About 20% of global seaborne crude oil passes through the Strait of Hormuz, and this disruption was immediately reflected in crude oil and jet fuel prices.
Jet fuel prices surged by about 95% since the conflict began, to approximately $4.51 per gallon by late April 2026, more than double the $2.24 assumed in the restructuring plan. According to J.P. Morgan analysis, if fuel prices remain at $4.60 per gallon, the projected +0.5% operating margin would immediately turn to negative 20%. The estimated additional fuel cost is about $360 million per year, an amount the carrier is entirely unable to absorb.
Here, Spirit's situation needs to be placed in the context of the entire industry. The Hormuz crisis affected all airlines, not Spirit alone. However, the impact was not evenly distributed. Large airlines with operating profit margins of 8 to 12%, with fuel hedging programs covering 30 to 50% of demand, with the financial resources to absorb short-term shocks, and with the ability to adjust fares (pricing power) thanks to a less price-sensitive customer segment, were able to get through the period of high fuel prices without facing an existential threat. Spirit, with a profit margin near zero, with no fuel hedge, with financial resources depleted after two bankruptcies, and with an extremely price-sensitive customer segment (unable to raise fares sharply without losing customers), was pushed to the edge.
From a systems perspective, the Hormuz event is an example of an "exogenous shock", a type of event that falls outside the normal probability distribution used for planning. However, for the aviation industry, geopolitical events affecting oil prices are not rare. The 1973 oil crisis, the 1990 to 1991 Gulf War, September 11, the 2008 financial crisis, the Covid-19 pandemic — every decade has at least one event that causes major disruption to the industry. Therefore, the question is not whether an unexpected event will occur, but whether the operating model is flexible enough to absorb the impact when it does. In Spirit's case, the answer was no, and this reflects operating structure rather than bad luck.
THE FINAL JOURNEY AND THE DISINTEGRATION OF THE OPERATING SYSTEM
After fuel prices surged, Spirit Airlines sought a federal rescue package worth $500 million in the form of a loan convertible into an equity stake of up to 90% in the airline. However, bondholders rejected these terms because the deal would place the government's interests ahead of existing creditors. The rescue package was not approved. With revenue insufficient to cover operating costs at current fuel prices, with no additional financing, and with little certainty that fuel prices would fall quickly, Spirit's leadership made the decision to cease operations.
The manner of the shutdown also contains noteworthy operational lessons. Notifying 17,000 employees just one hour before the decision was announced (the leadership of the Association of Flight Attendants, abbreviated AFA, sent notice to 5,000 members at Spirit at around 1 a.m. Eastern Time) shows the urgency of the situation, while also reflecting the limits of transition planning capability when an organization is in a state of acute crisis. Under ideal conditions, an orderly wind down allows time to support employees through the transition, fulfill obligations to customers who had booked tickets, and preserve the value of transferable assets. However, when a business is losing money every day it operates, each day of delay in ceasing operations means additional financial losses, creating pressure to act quickly.
Spirit Airlines' shutdown also created a ripple effect across the entire U.S. aviation system. Hundreds of thousands of passengers who had booked tickets on Spirit needed to be re-accommodated on other carriers. Airports where Spirit accounted for a significant share of capacity, especially Fort Lauderdale Hollywood International Airport (FLL), where Spirit was once the largest airline with about 65 domestic flights per day, suddenly lost a significant portion of traffic. JetBlue immediately announced 11 new routes from Fort Lauderdale to fill the gap. Aviation employees, especially pilots and flight attendants with professional certifications, entered the labor market all at once, creating both opportunities (for airlines that are hiring) and challenges (for the workers themselves during the transition).
ANALYSIS FROM AN OPERATIONS OPTIMIZATION PERSPECTIVE
Looking back at Spirit Airlines' entire journey, you see not just a bankrupt airline, but an operating system that underwent a process of process capability degradation over many years before collapsing. Collapse is never sudden to those who know how to read signals from the system.
Confusing "operational efficiency" with "operational health."
This is the most common cognitive error in operations management practice, and Spirit Airlines is its clearest illustration. In operations optimization thinking, there is a fundamental difference between two concepts that many organizations often conflate. Operational efficiency answers the question: "Is the organization minimizing waste in its current processes?" While operational health answers the question: "Can the operating system sustain acceptable performance through multiple cycles of volatility?"
Spirit Airlines scored exceptionally high on operational efficiency. A uniform fleet, the lowest CASM in the industry, minimal turnaround times, maximum seat density — every process had been streamlined to the point where there was almost nothing left to cut. But operational health was a completely different story. Operational health can be understood as an organization's immune system. A person can run very fast (high efficiency), but if their immune system is weakened, even a common cold can lead to serious complications. Spirit ran faster than any other airline on a straight track, but its operational immune system — its ability to withstand and recover from shocks — had deteriorated to a dangerous level.
When assessing an organization's operational health, you need to look at five leading indicators, the signals that tell you a system will run into trouble before the trouble actually happens — unlike lagging indicators such as profit, revenue, or on-time performance, which only tell you what has already happened. Those five indicators are: capacity buffer margin (how much capacity can be lost before the system stops functioning), cost adaptation speed (when revenue falls by 10%, how quickly and by how much costs can be reduced), risk-source diversification (how many independent variables could trigger a collapse), financial buffer depth (how many months the organization can survive at zero revenue), and organizational learning capability (how quickly the organization can change its processes once it recognizes a problem). If you had applied these five indicators to Spirit in 2023, before any major shock had occurred, the result would have been a red alert on almost every indicator.
The local optimization trap and the phenomenon of “sub-optimization.”
In systems thinking, there is a principle that Dr. W. Edwards Deming emphasized repeatedly in his System of Profound Knowledge: optimizing each individual part of a system does not lead to optimization of the whole system, and in many cases, it even makes the whole system worse. This is precisely the phenomenon of sub-optimization.
Spirit Airlines optimized each individual component brilliantly: fuel cost per ASM was minimized with a new, efficient fleet, labor cost per ASM was controlled through high labor productivity, distribution costs were reduced through direct sales, and airport costs were reduced through short turnaround times. But viewed as a whole system, this part-by-part optimization created a rigid system lacking the ability to self-adjust. Each function was already running at the maximum limit of its design capacity, with no slack left to compensate when another function ran into trouble.
The easiest image is a race car tuned to run fastest on one specific track, with tire pressure, gear ratios, wing angle, and fuel load all optimized for exactly that track, at that air temperature, at that humidity. The car will run faster than every rival on that track. But if it rains, or one corner of the track changes, or the temperature shifts by 10 degrees, that extremely optimized car will lose competitiveness faster than a car tuned to be “good enough” for many conditions. That is exactly the paradox Spirit faced: the airline was the fastest race car on a dry track, but it had been raining since 2019 — and raining ever harder.
“Common cause” vs. “special cause” variation: how to read signals from the system.
One of the core capabilities of a Master Black Belt is the ability to distinguish between common cause variation and special cause variation in operational data. Common cause variation is inherent to the system, lies within control limits, and can only be reduced by changing the system. Special cause variation is caused by a specific, identifiable event and falls outside normal control limits.
Applying this lens to Spirit Airlines, two types of variation operating simultaneously become clear. Common cause variation included the gradual divergence of CASM/RASM, the gradual erosion of competitive advantage as legacy carriers rolled out Basic Economy, the industry-wide gradual rise in labor costs, and the gradual shift in post-pandemic consumer behavior as passengers began to value reliability and experience more highly. These are structural trends, caused not by any single event but by the natural evolution of the market. To respond to common cause variation, you must change the system — that is, change the business model, redesign the value chain, or reposition the brand.
Special cause variation included the P&W GTF engine issues, the blocked JetBlue merger, and the Strait of Hormuz crisis. These were specific, identifiable events with clear impact. To respond to special cause variation, you need to isolate and address the specific root cause.
The most common strategic mistake that Deming called “tampering” is when an organization responds to common-cause variation with a special-cause action, or vice versa. In Spirit’s case, the first Chapter 11 restructuring can be analyzed through this lens: the airline treated the financial consequences (a symptom) with a balance-sheet restructuring (a special-cause countermeasure), while the real problem was a structural shift in the market and the business model (a common cause) that demanded a comprehensive system-level change.
Value Stream Thinking and “value” in the eyes of the customer.
A foundational question when analyzing any operating system is: “Is value in the eyes of the customer changing, and is the operating system changing with it?” Spirit Airlines defined value for customers as the lowest possible fare, and built its entire value chain around that definition. That was entirely reasonable at the time the model was designed.
But the definition of “value” in the eyes of the customer is not a constant. After the Covid-19 pandemic, U.S. airline consumer behavior changed noticeably. Customers began to weigh the total cost of experience rather than just the ticket price. The total cost of experience includes: the base fare plus baggage fees, seat-selection fees, food charges, plus risk cost (the probability of cancellation, delay, lost baggage, and having to fend for yourself during disruptions), plus opportunity cost (no mileage accrual, no loyalty benefits, no flexible rebooking support). When legacy carriers sold Basic Economy tickets priced only 15 to 25 dollars higher than Spirit’s but bundled with an extensive connecting network, mileage programs, and support during disruptions, the total cost of experience on legacy carriers was actually lower than Spirit’s in many cases, even though the nominal fare was higher.
This has profound operational implications. When customers change how they define value, but the operating system remains optimized for the old definition of value, that system is producing something the market is increasingly less willing to pay for, no matter how efficiently it is produced. Efficiently producing something customers no longer want to buy is the greatest form of waste in lean operations thinking — it is overproduction waste at the strategic level.
A one-way supply chain and the concept of “single point of failure” at the system level.
When analyzing Spirit’s dependence on Pratt & Whitney GTF engines, many see it as a simple supplier issue. But from a Master Black Belt perspective, this is a symptom of a deeper problem: Spirit had too many single points of failure across its entire operating system.
The list of single points of failure includes: a single engine type (PW1100G JM), a single aircraft manufacturer (Airbus), a single business model (pure-play ULCC), a single core customer segment (highly price-sensitive), a single core source of competitive advantage (the lowest price), and a single core geographic market (the U.S. domestic market and the Caribbean). Each “single” in this chain is a single point of failure. In reliability engineering, the basic principle is: the overall reliability of a series system equals the product of the reliability of each component. With six components in series, each with 90% reliability (meaning a 90% probability of operating normally in a given cycle), the overall system reliability is 0.9 to the power of 6, or about 53%. That means the system has nearly a fifty-percent probability of experiencing at least one failure in each cycle. This is not abstract mathematics but the reality Spirit lived through when multiple single points of failure developed problems at the same time.
Negative-direction positive feedback loops and “accelerating decline.”
An important characteristic of Spirit’s collapse that needs to be recognized is the formation of positive feedback loops in a negative direction — that is, each problem makes the other problems worse, creating an accelerating-decline effect.
The specific chain of impacts: GTF issues → reduced fleet capacity → fewer flights → lower revenue → cost cuts → lower service quality → lower load factor → further revenue decline → difficulty attracting investment capital → no money to hedge fuel risk → greater vulnerability to fuel-price volatility → when fuel prices rise, the impact is heavier → deeper losses → inability to pay. Once this loop starts, it is very difficult to break because every effort to solve one problem is obstructed by the other problems in the loop.
In systems thinking, the only way to break a negative positive feedback loop is to intervene at the leverage point of the system — that is, to find the point where a small change can create the greatest impact on the entire loop. For Spirit, the leverage point was probably its business model (shifting from a pure ULCC to a hybrid model serving more diverse customer segments), but changing the business model while caught in a downward spiral requires resources the airline no longer had. This is what in consulting practice is called a "closed intervention window": the moment when change could still have created a positive impact has passed, and the organization is left with only less-bad options rather than good ones.
The "business optimized for yesterday" problem.
There is a useful concept when analyzing organizations in distress: "yesterday's optimized enterprise". This is a condition in which an organization has built an operating system perfect for a business environment that no longer exists. Every process, every capability, every organizational structure was designed for a reality that has passed, and the opportunity cost of maintaining the old system keeps growing larger than the benefits it delivers.
Spirit Airlines was a business optimized for the 2007 to 2019 period, when fuel prices were relatively stable, when there was no Basic Economy from legacy carriers, when US passengers were shifting toward a "pay for what you need" mindset, and when competition in the ULCC segment was still limited. By 2023, every one of those conditions had changed, but its operating system was still designed for the old context.
The deeper lesson here is not that Spirit was wrong to build the ULCC model. That model was entirely right for its time and context. The lesson is: every operating model has a "design life", just like bridges, machinery, or any engineered system. When the design life expires, it is not because the system is broken, but because the conditions the system was designed to operate in have changed enough that the system needs to be redesigned, not merely maintained or further optimized. Continuing to optimize a model whose design life has expired is like perfectly maintaining a typewriter in the computer age: the typewriter may run better than ever, but no one needs it anymore.
REFLECTIONS ON DESIGNING OPERATING SYSTEMS IN A VOLATILE ENVIRONMENT
From the analysis above, the following seven reflections are for any operations leader running an organization in a highly volatile environment. These are not theory, but lessons drawn from the Spirit Airlines case, placed in the broader context of operations optimization practice.
Reflection one: Measure "distance to failure" instead of only measuring current performance.
Most operational dashboards in organizations focus on current performance: today's revenue, this month's costs, this quarter's profit. Very few organizations measure and track distance to failure from the current state. The breaking point is the threshold at which the system loses its ability to self-recover: "How much further can fuel prices rise before margins turn negative?", "What percentage of the fleet can be grounded before the network starts to collapse?", "How many months of consecutive losses can the organization absorb before running out of liquidity?" If Spirit had regularly measured and reported distance to failure for critical variables, leadership would have seen that distance shrinking every quarter, creating pressure to act earlier, while the intervention window was still open.
Reflection two: Build "operational switchability" as a core capability.
Most organizations build core capabilities around operating the current model (doing what they do better). Very few build core capabilities around switching models (moving from one way of operating to another). The concept of "operational switchability" refers to the ability to move between different operating modes depending on environmental conditions.
In aviation, an instructive example is Ryanair in Europe, also a ULCC but one that built stronger switching capability than Spirit. Ryanair maintains a fuel hedge program covering up to 80% of demand for the next 12 months, allowing it to shift between "low fuel price" and "high fuel price" modes without shock. Ryanair also maintains a low debt-to-equity ratio, creating a financial buffer to absorb shocks. And most importantly, Ryanair operates in the European market where ULCC competition differs from that in the United States, showing that the same operating model in a different ecosystem context will produce different results.
Reflection three: Distinguish between "value-creating savings" and "savings borrowed from the future."
Not all cost savings are created equal. In operations optimization, there is a fundamental difference between value-creating savings (eliminating true waste, improving processes, increasing productivity) and savings borrowed from the future (deferring maintenance, reducing training, cutting buffers, not hedging fuel). The first type of savings makes the organization stronger over time. The second makes the organization appear stronger right now but accumulates “operational debt”, similar to the concept of “technical debt” in software development — hidden costs that will have to be paid in the future, often at interest rates far higher than the initial savings.
When Spirit Airlines did not build a meaningful fuel hedging program, that was a form of immediate cost saving (no derivatives contract fees to pay) but at the same time a loan borrowed from the future (accepting the full risk of fuel price volatility). When the future arrived in the form of the Hormuz crisis, that debt “matured” at an extremely high “interest rate.”
Fourth reflection: Financial restructuring does not replace operational restructuring.
This lesson needs to be emphasized because it is so common. In practice, most restructurings focus too much on the financial side and too little on the operational side. The reason is very simple: financial restructuring produces immediately measurable results (X billion in debt reduced, Y million in annual interest saved), while operational restructuring produces results spread over time and difficult to quantify in advance. Under pressure from the bankruptcy court, creditors, and time, organizations naturally lean toward the solution that delivers quick results. But if the root cause lies in the operating model, then financial restructuring is like pain relief without curing the disease: the patient feels better temporarily, but the illness keeps progressing.
Fifth reflection: “Resilience” is an investment, not a cost.
When an organization maintains spare capacity, diversifies suppliers, builds a hedging program, or holds more cash than needed for day-to-day operations, these actions are often seen as “costs” because they do not create direct value under normal conditions. But this perception needs to be corrected. Resilience is a form of operational insurance, and like insurance, its value is only revealed when an adverse event occurs.
The right way to evaluate the value of resilience is to calculate it over the full cycle, including both normal years and crisis years, not just a single normal year. If the cost of maintaining resilience is 2% of revenue per year for 10 years (20% of revenue in total), but it prevents an event that could destroy 50% of enterprise value, then it is an investment with a clearly positive return. Spirit Airlines saved on hedging costs, buffer costs, and diversification costs for many years, but when the shock hit, those accumulated savings were not equal to even a small fraction of the losses.
Sixth reflection: A “problem-solving” culture versus a “problem-preventing” culture.
Two types of operating culture need to be distinguished. A reactive culture is when an organization is good at responding when incidents occur: assembling teams, analyzing quickly, developing solutions, and remediating consequences. A preventive culture is when an organization invests in identifying and preventing problems before they occur: continuously monitoring leading indicators, conducting regular scenario analysis, building early-warning systems, and maintaining contingency plans for adverse scenarios. A problem-solving culture looks very impressive from the outside because everyone sees heroic efforts and spectacular crisis resolution. But a problem-preventing culture, though less “dramatic,” is the culture that creates a sustainable organization for the long term. The best organization is one that never needs heroes, because the system has been designed to handle most disruptions automatically and according to plan.
Seventh reflection: People are always at the center of every operating system.
The final reflection, but perhaps the most important one. The most frequent questions in operations optimization meetings are: “How can we cut costs further?”, “How can we increase productivity?”, “How can we automate processes?” Very rarely is the question asked: “How can the operating system better serve all stakeholders, including employees, customers, communities, and investors?”
17,000 people losing their jobs from the Spirit Airlines event is not a side effect; it is the direct result of how the operating system was designed. An operating system designed only to optimize a single financial metric (CASM, profit margin, stock price) while ignoring sustainability for all stakeholders will create short-term value but can destroy long-term value on a far larger scale. The ultimate goal of operations optimization is not to create the most efficient organization possible, but to create an organization that is both efficient and sustainable, where economic performance and responsibility to people are not two opposing ends of a scale, but two pillars holding up the same roof.
Disclaimer: This article is written solely for academic analysis and professional knowledge-sharing in the field of Operational Excellence. All content is based on public sources including SEC filings, financial reports, and reputable news outlets at the time of writing. The author does not represent any organization, airline, or related party mentioned in this article. This article is not intended to criticize, assign blame, provide investment advice, legal counsel, or pass judgment on any individual or organization. All analyses, observations, and reflections reflect a purely operational professional perspective and are for reference only. Figures may change as newer information becomes available. The author acknowledges and respects the 17,000 Spirit Airlines employees and their families who were directly affected by this event.
Image is for illustration purposes only.
DBA John Ngo | Lean Six Sigma Master Black Belt | 40 under 40 Operational Excellence expert honored by the American Society for Quality (ASQ) in 2021 | Founder & Professional Director at John&Partners: Consulting | Coaching | Training in Operational Excellence.
REFERENCE LIST
Spirit Airlines — “Spirit Airlines Wikipedia”: https://en.wikipedia.org/wiki/Spirit_Airlines
CBS Detroit — “Spirit Airlines traces its roots to Metro Detroit, where it launched as a charter service in 1983”: https://www.cbsnews.com/detroit/news/spirit-airlines-origin-metro-detroit/
AeroXplorer — “The History of Spirit Airlines: From 1983 to Now”: https://aeroxplorer.com/articles/the-history-of-spirit-airlines-from-1983-to-now.php
FundingUniverse — “History of Spirit Airlines, Inc.”: https://www.fundinguniverse.com/company-histories/spirit-airlines-inc-history/
Airways Magazine — “Ben Baldanza: The Spirit of ULCC Innovation in the US”: https://www.airwaysmag.com/new-post/ben-baldanza-spirit-ulcc-innovation-us
Mighty Travels — “Spirit Airlines’ Evolution From Charter Flights to Ultra Low Cost Giant”: https://www.mightytravels.com/2024/08/spirit-airlines-evolution-from-charter-flights-to-ultra-low-cost-giant/
Visual Approach Analytics — “Spirit’s RASM/CASM chasm”: https://visualapproach.io/spirits-rasm-casm-chasm/
Visual Approach Analytics — “Spirit’s RASM/CASM chasm (newsletter)”:
https://weekly.visualapproach.io/p/spirits-rasm-casm-chasm
Santiago & Company — “Spirit Airlines and the Anatomy of an Optionality Failure”: https://www.santiagocompany.com/insights/spirit-airlines-and-the-anatomy-of-an-optionality-failure
SimpleFlying — “Spirit Airlines Reports $1.2 Billion Loss For 2024 With Plans For Recovery”: https://simpleflying.com/spirit-airlines-1-billion-loss-2024-plans-recovery/
Aviation News Online — “Spirit Airlines’ 2024 revenues down 8%, received $151 million in credits related to GTF engine issue”: https://aviationnews-online.com/public/article/spirit-airlines-full-year-revenues-down-8
FlightGlobal — “Engine issues and lease terminations among forces driving Spirit’s latest bankruptcy filing”: https://www.flightglobal.com/strategy/engine-issues-and-lease-terminations-among-forces-driving-spirits-latest-bankruptcy-filing/164350.article
Skift — “Spirit Airlines to Receive up to $200 Million for Pratt & Whitney Engine Problems”: https://skift.com/2024/03/29/spirit-airlines-to-receive-compensation-for-pratt-and-whitney-engine-issues/
Aviation A2Z — “Spirit Airlines Gets $150 Million Compensation Amid P&W Engine Problems”: https://aviationa2z.com/index.php/2025/03/04/spirit-airlines-gets-150-million-compensation-from-pw/
SimpleFlying — “Spirit Airlines Backtracks On Plan To Furlough Up To 365 Pilots Next Quarter”: https://simpleflying.com/spirit-airlines-backtracks-furlough-365-pilots/
Airways Magazine — “Spirit Halts Growth Plans, Downgrades, Furloughs Pilots”: https://www.airwaysmag.com/new-post/spirit-halts-growth-downgrades-furloughs-pilots
Justice Department — “Justice Department Statements on JetBlue Terminating Acquisition of Spirit Airlines”: https://www.justice.gov/archives/opa/pr/justice-department-statements-jetblue-terminating-acquisition-spirit-airlines
Holland & Knight — “2025 Aviation Bankruptcy Update”: https://www.hklaw.com/en/insights/publications/2026/02/2025-aviation-bankruptcy-update
CNBC — “Spirit Airlines files for Chapter 11 bankruptcy protection for the second time in a year”: https://www.cnbc.com/2025/08/29/spirit-airlines-chapter-11-bankruptcy.html
NPR — “Spirit Airlines files for bankruptcy for 2nd time in less than a year”: https://www.npr.org/2025/08/30/nx-s1-5522901/spirit-airlines-bankruptcy-filing
Fortune — “Spirit Airlines looked like it was in the clear of reemerging from bankruptcy, but rising fuel costs threaten its exit”: https://fortune.com/2026/04/20/spirit-airlines-bankruptcy-exit-jet-fuel-liquidation/
MMCGInvest — “Spirit Airlines at the Cliff Edge: Assumption Brittleness and the Arithmetic of the April 2026 Plan”: https://www.mmcginvest.com/post/spirit-airlines-at-the-cliff-edge-assumption-brittleness-and-the-arithmetic-of-the-april-2026-plan
Globe and Mail — “Spirit Airlines shuts down after oil price spike derailed restructuring plan”: https://www.theglobeandmail.com/business/international-business/article-spirit-airlines-shuts-down-iran-war-oil-price-spike/
Al Jazeera — “Spirit Airlines begins ‘wind down’, cancels all flights over fuel crisis”: https://www.aljazeera.com/news/2026/5/2/spirit-airlines-begins-wind-down-cancels-all-flights-over-fuel-crisis
CBC News — “Spirit Airlines shuts down, blames cost of fuel due to Middle East war”: https://www.cbc.ca/news/world/spirit-airlines-ceasing-operations-9.7185446
CNBC — “Spirit Airlines shuts down after failing to reach a bailout deal, ending discount travel era”: https://www.cnbc.com/2026/05/01/spirit-airlines-trump-bailout.html
CNN — “Spirit Airlines canceled all flights and is going out of business”: https://www.cnn.com/2026/05/02/business/spirit-to-halt-all-flights
PBS News — “Spirit Airlines goes out of business after 34 years, ceases operations immediately”: https://www.pbs.org/newshour/economy/spirit-airlines-goes-out-of-business-after-34-years-ceases-operations-immediately
NPR — “Spirit Airlines ceases operations after escalating financial struggles”: https://www.npr.org/2026/05/02/nx-s1-5807933/spirit-airlines-ceases-operations-folds
CNBC — “Spirit Airlines’ final hours: ‘Godspeed my friend’ as terminals go dark”: https://www.cnbc.com/2026/05/02/spirit-airlines-shutdown-inside-the-final-hours.html
NPR — “Spirit Airlines shutters after federal bailout falls through”: https://www.npr.org/2026/05/04/nx-s1-5808972/spirit-airlines-shutters-after-federal-bailout-falls-through
Fortune — “Spirit Airlines is ending operations immediately and going out of business after 34 years”: https://fortune.com/2026/05/02/spirit-airlines-bankruptcy-going-out-of-business-flight-refunds-rebooking/
SimpleFlying — “Why Low Cost Airlines Struggle To Compete With Basic Economy Fares”: https://simpleflying.com/low-cost-airlines-vs-legacy-carriers-basic-economy-analysis/
NPR/KPBS — “Spirit Airlines tried to be the Dollar General of the skies. Then the big airlines beat it at its own game”: https://www.kpbs.org/news/economy/2026/04/29/spirit-airlines-tried-to-be-the-dollar-general-of-the-skies-then-the-big-airlines-beat-it-at-its-own-game
Marketplace — “How ultra low cost carriers like Spirit lost customers to the major airlines”: https://www.marketplace.org/story/2026/04/30/how-ultra-lowcost-carriers-like-spirit-lost-customers-to-the-major-airlines
The Points Guy — “JetBlue moves quickly to fill Spirit’s gap, adds 11 routes from Fort Lauderdale”: https://thepointsguy.com/news/jetblue-fort-lauderdale-11-new-routes-spirit-airlines/
Wikipedia — “2026 Strait of Hormuz crisis”: https://en.wikipedia.org/wiki/2026_Strait_of_Hormuz_crisis
Wikipedia — “2026 Iran war fuel crisis”: https://en.wikipedia.org/wiki/2026_Iran_war_fuel_crisis
DDS Finance — “Spirit Airlines Is Dead: How a $5B Carrier Burned Through $930M of Annual Cash”:

CNBC — “Spirit Airlines is on shakier ground after avoiding hard decisions in bankruptcy”: https://www.cnbc.com/2025/08/21/spirit-airlines-lessors-bankruptcy.html
Case Study
More from this section
 Plus
Operational Excellence (OPEX) Insight – Tuesday - November 03, 2026: Looks Like a Jump, but Not Really Selling More
 Pro
Operational Trends | #06: AI's Bottleneck Has Moved From Chips to Power.
 Plus
Operational Excellence (OPEX) Insight – Thursday - October 29, 2026: Prices Up, Volume Down, Margins Still Fatter
 Plus
Operational Excellence (OPEX) Insight – Tuesday - October 27, 2026: Profit on Paper, Cash in Reality
 Pro
Operational Trends | #05: Humans Move From Operator to Overseer.
 Plus
Operational Excellence (OPEX) Insight – Thursday - October 22, 2026: Tesla Sells Cars, Earns on Batteries
 Pro
Operational Trends | #04: Buying AI Is Easy, Cleaning the Data Is Hard.
 Pro
Comments 0
No comments yet. Be the first.